What is the defining scope and industry significance of the Border Security Market?
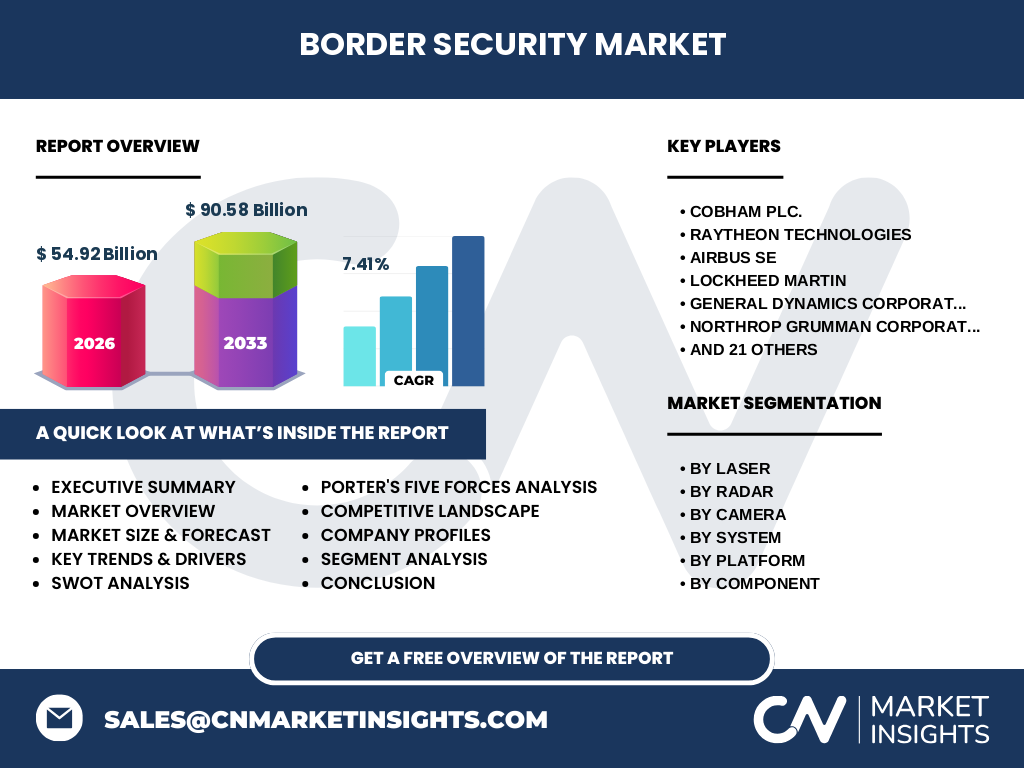
Our analysis indicates the Border Security Market represents a critical defense sector valued at 54.92 Billion in 2026. This ecosystem encompasses advanced technological solutions deployed across land ports, maritime ports, and aviation hubs to safeguard national sovereignty against transnational threats, illegal migration, and smuggling.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating geopolitical tensions and rising illicit cross-border trafficking, which force governments to upgrade legacy infrastructure. Restraints include high upfront capital expenditures for deployment, while strict compliance mandates from regulatory bodies such as the Department of Homeland Security create significant integration challenges for contractors.
The Shift Toward Autonomous and Integrated Surveillance
Emerging growth patterns highlight a decisive migration toward unmanned systems, thermal imaging cameras, and AI-driven security management software. Defense innovators like Elbit Systems and Israel Aerospace Industries are capitalizing on this by delivering sensor-to-shooter integration that drastically reduces human error in perimeter defense.
How did the COVID-19 pandemic reshape supply chains and recovery trajectories?
The pandemic severely disrupted global semiconductor supply chains, delaying the rollout of complex radar systems and cargo scanners. However, our research reveals an accelerated post-pandemic recovery, as governments prioritized touchless biometric systems and automated surveillance to maintain strict health screening alongside traditional threat detection.
Competitive Benchmarking and Industry Concentration
The competitive landscape features high concentration among defense primes like Lockheed Martin, Northrop Grumman Corporation, and Raytheon Technologies. These Tier-1 contractors leverage vast R&D budgets to dominate large-scale government contracts, forcing smaller technology specialists to pursue niche innovations or strategic acquisitions.
Executive Summary of the Border Security Market Report
Driven by compounding geopolitical risks and technological modernization, our research projects the Border Security Market to expand from 54.92 Billion in 2026 to reach 90.58 Billion by 2033, registering a robust 7.41% CAGR. Stakeholders must pivot toward integrated software and sensor fusion.
Market Forecast and Revenue Projections (2027 to 2033)
Based on our econometric modeling, the sector is poised for accelerated expansion, scaling from its 2026 baseline to 90.58 Billion by 2033. This trajectory represents a steady 7.41% CAGR, fueled by multi-billion-dollar modernization initiatives across North American and European land and maritime borders.
Segmentation Analysis across Systems, Platforms, and Components
The market is structurally segmented by laser, radar, camera, and perimeter intrusion components deployed across land ports, ports, and aviation platforms. Specialized hardware like cargo scanners and elemental isotope detectors play vital roles in freight screening, while software management suites unify disparate data streams.
Geographic Distribution and Regional Performance
Geographically, demand is heavily concentrated in regions facing persistent territorial disputes and immigration pressures. North America leads consumption due to extensive modernization along major land borders, while the Asia-Pacific region demonstrates the fastest growth trajectory driven by maritime security concerns in regional waterways.
In-Depth Regional Review of High-Growth Zones
Our regional audit shows North America commanding the largest revenue share, supported by robust defense budgets and established contractors like L3Harris Technologies and General Dynamics Corporation. Meanwhile, European investments are surging under Frontex mandates, boosting demand for advanced satellite surveillance and ground sensors.
Strategic Positioning of Leading Companies
Industry leaders occupy distinct strategic niches: Thales Group and Safran SA excel in optronics and radar, whereas Palantir Technologies dominates big-data analytics for intelligence fusion. Firms like Smiths Detection and Rapiscan Systems specialize exclusively in high-throughput cargo and baggage screening infrastructure.
Porter's Five Forces Assessment of Competitive Pressures
The threat of new entrants remains low due to stringent government clearance protocols and high capital barriers. However, buyer power is high because defense ministries dictate contract terms, while supplier power is moderate, resting heavily on specialized semiconductor and sensor component manufacturers.
SWOT Analysis of the Border Security Ecosystem
Key strengths include proprietary sensor fusion and advanced biometrics, while weaknesses involve long government procurement cycles. Opportunities lie in AI-driven predictive analytics, whereas threats stem from sophisticated cyber-attacks targeting critical infrastructure networks and supply chain vulnerabilities.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material providers supplying rare-earth elements and semiconductors, flowing into component manufacturers producing lasers and thermal imaging cameras. Tier-1 integrators then assemble these into comprehensive perimeter intrusion systems for deployment by border patrol end-users.
Investment Insights and High-Potential Opportunity Areas
Investors should target agile innovators specializing in security management software and AI-driven anomaly detection. Companies capable of retrofitting legacy fencing and radar systems with modern software layers offer the highest potential for margin expansion and strategic acquisition interest.
Conclusion and Strategic Key Takeaways
The transition toward automated, software-defined border defense is irreversible. Reaching 90.58 Billion by 2033 at a 7.41% CAGR, the market rewards enterprises that successfully integrate multi-layered sensor data with real-time analytics to mitigate evolving global security threats.
Research Methodology and Data Triangulation
Our baseline estimates are derived through rigorous data triangulation, combining trade registry statistics, primary stakeholder interviews with defense procurement officers, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in market sizing and segment-level revenue forecasts.
Scope of the Report and Analytical Parameters
This report covers global deployment dynamics across land ports, aviation, and maritime platforms through 2033. While comprehensive, the analysis excludes classified black-budget military programs and strictly focuses on publicly disclosed government expenditures and commercial border protection contracts.
Recent Industry Developments, Partnerships, and Product Launches
Recent strategic moves highlight heavy consolidation and technological leapfrogging, exemplified by Teledyne's acquisition of FLIR Systems and L3Harris absorbing Harris Corporation. Concurrently, firms are aggressively launching AI-enabled unmanned aerial systems to patrol porous borders without risking personnel.